CSRD 2026 deadlines by company size: who reports for FY2025, FY2026 and FY2027 after Omnibus I
The CSRD phase-in written in 2022 no longer applies as written. Two directives changed it: Directive (EU) 2025/794 (stop the clock, April 2025) pushed the second and third waves back two years, and Directive (EU) 2026/470 (Omnibus I, published 26 February 2026, in force 18 March 2026) raised the scope thresholds and removed listed SMEs. This page gives the position by company size as it stands in September 2026, with the article for each line. It is refreshed when the rule moves.
The scope from FY2027: two thresholds, both exceeded
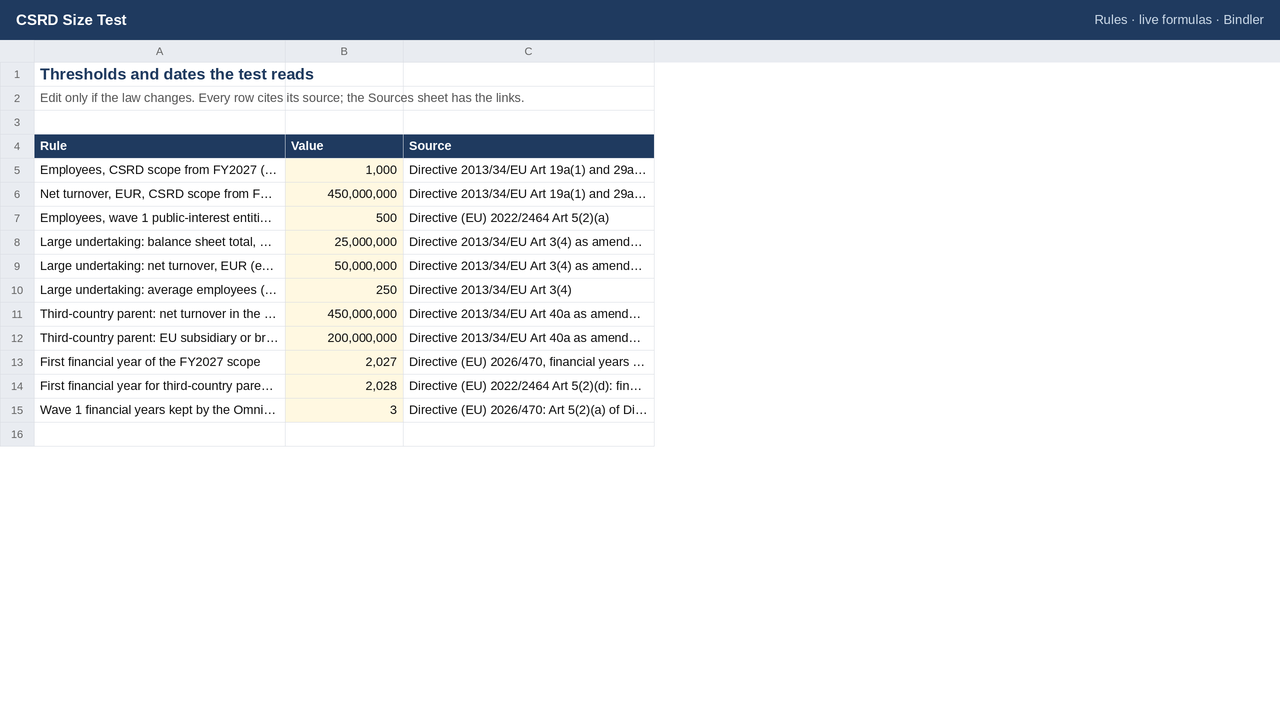
From financial years starting on or after 1 January 2027, a company reports under the CSRD if it is a large undertaking or parent of a large group that exceeds, on average over the financial year, both 1 000 employees and EUR 450 million net turnover (Directive 2013/34/EU, Articles 19a(1) and 29a(1), as amended by Directive (EU) 2026/470). A company with 3 000 employees and EUR 300 million turnover is out. So is one with EUR 2 billion turnover and 800 employees. Exactly 1 000 employees or exactly EUR 450 million is not exceeded.
"Large undertaking" keeps its Accounting Directive meaning: exceeding two of EUR 25 million balance sheet, EUR 50 million net turnover and 250 employees (Article 3(4), thresholds as raised by Delegated Directive (EU) 2023/2775). Being large is necessary but no longer sufficient.
By company size and year
| Company | FY2024 | FY2025 | FY2026 | FY2027 onward |
|---|---|---|---|---|
| Public-interest entity (listed on an EU regulated market, bank or insurer) with more than 500 employees, and above 1 000 employees and EUR 450m turnover | Reports (wave 1, report published 2025) | Reports | Reports | Reports |
| Public-interest entity with more than 500 employees but not above both new thresholds | Reports (wave 1) | Reports unless its Member State uses the exemption option | Reports unless its Member State uses the exemption option | Out |
| Other large undertaking or group above 1 000 employees and EUR 450m | No | No (wave 2 postponed by stop the clock) | No | Reports, first report published in 2028 |
| Other large undertaking or group not above both thresholds | No | No | No | Out |
| SME listed on an EU regulated market | No | No | No | Out (removed by Omnibus I) |
| Non-EU parent with EUR 450m net turnover in the EU in each of the last two financial years and an EU subsidiary or branch above EUR 200m | No | No | No | FY2028 under Article 40a as written in Directive (EU) 2022/2464 Article 5(2)(d); confirm the date in the transposing law |
Notes on the table:
- Wave 1 stays in for three financial years from 1 January 2024 (FY2024, FY2025, FY2026) under Directive (EU) 2026/470, but Member States may exempt wave-1 entities that fall below the new thresholds from reporting for FY2025 and FY2026. Whether your Member State has used that option is a national-law question; the directive only allows it.
- Wave 2 (other large undertakings) was to start with FY2025 and was postponed two years by Directive (EU) 2025/794. Under Omnibus I it now begins with FY2027 and only for those above both thresholds.
- Wave 3 (listed SMEs) was postponed to FY2028 by stop the clock and then removed from scope altogether by Omnibus I.
- Reports are published with the management report, so an FY2027 report reaches the public in 2028, within the same deadline as the annual financial statements in that Member State.
The other dates that moved
- Assurance stays at limited assurance; the Commission adopts the limited assurance standard by 1 July 2027 (Directive (EU) 2026/470). The planned move to reasonable assurance is gone.
- ESRS revision: the simplified standards are due by 18 September 2026.
- Transposition: Member States have until 19 March 2027 to bring Omnibus I into national law. Until then the national text may still show the old thresholds; the directive's dates govern what is coming.
- Value chain: a company in scope may not ask a supplier with up to 1 000 employees for more than the voluntary standard's data points (Article 19a(3)).
Test your own company in a minute
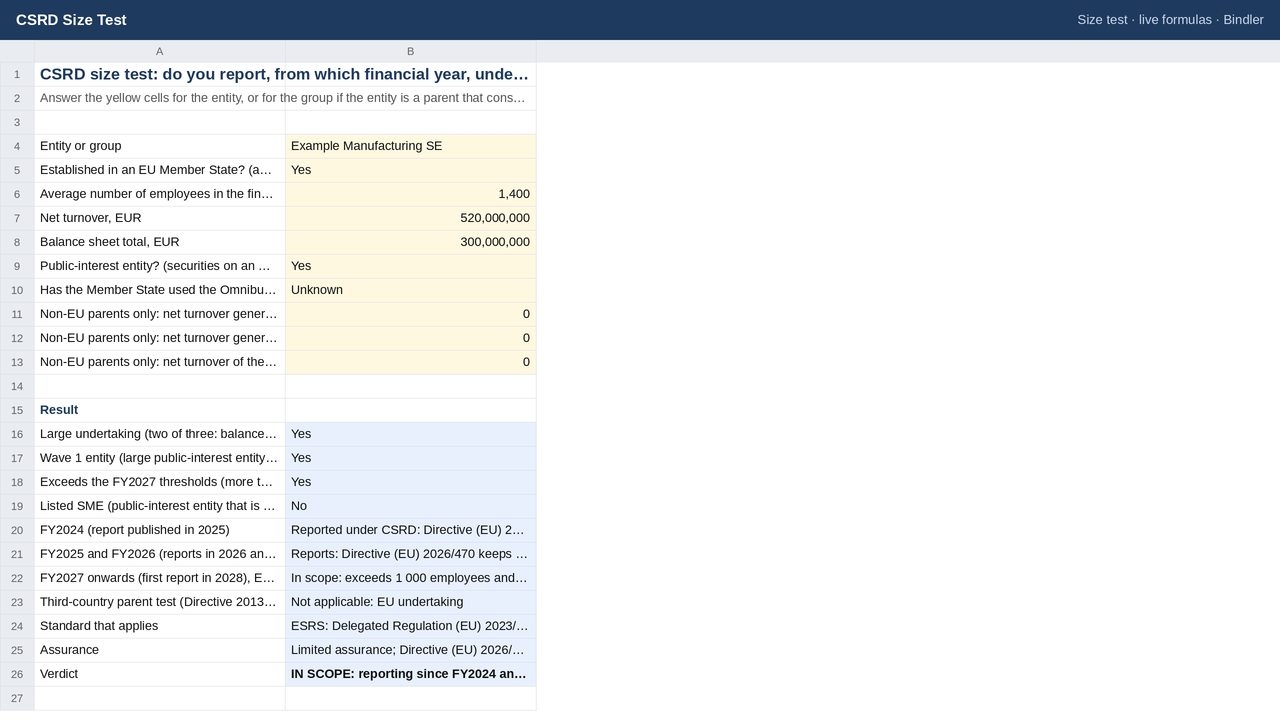
The $1 CSRD Size Test is one sheet: employees, net turnover, listing status, public-interest status and parent location in, and out come whether you report, from which financial year, under which article. Every threshold sits on a Rules sheet with its source, so when the transposing law lands you change one cell.
Once you are in, the double materiality template is the first workbook you need.
Sources
- Directive (EU) 2026/470 (Omnibus I), OJ 26 February 2026, in force 18 March 2026: eur-lex.europa.eu/eli/dir/2026/470/oj.
- Directive (EU) 2025/794 (stop the clock): eur-lex.europa.eu/eli/dir/2025/794/oj.
- Directive (EU) 2022/2464 (CSRD), Article 5(2), the original phase-in: eur-lex.europa.eu/eli/dir/2022/2464/oj.
- Directive 2013/34/EU, Articles 2(1), 3, 19a, 29a and 40a: eur-lex.europa.eu/eli/dir/2013/34/oj.
- Commission Delegated Directive (EU) 2023/2775, the size thresholds: eur-lex.europa.eu/eli/dir_del/2023/2775/oj.
Last checked against the sources on 19 September 2026.
Search terms this page answers: csrd 2026 deadlines, csrd deadlines by company size, csrd omnibus 1000 employees 450 million, who has to report under csrd 2027, csrd wave 1 wave 2 dates after omnibus, csrd first report due date.